
The 2026 increase, and what comes next
By law, VA matches the cost-of-living adjustment (COLA) the Social Security Administration gives. On October 24, 2025, SSA announced a 2.8 percent increase for 2026 (it was 2.5 percent for 2025). VA disability compensation rose 2.8 percent effective December 1, 2025, under Public Law 119-42. A veteran rated 100 percent with no dependents now receives $3,938.58 a month; a veteran rated 30 percent with a spouse receives $617.47.
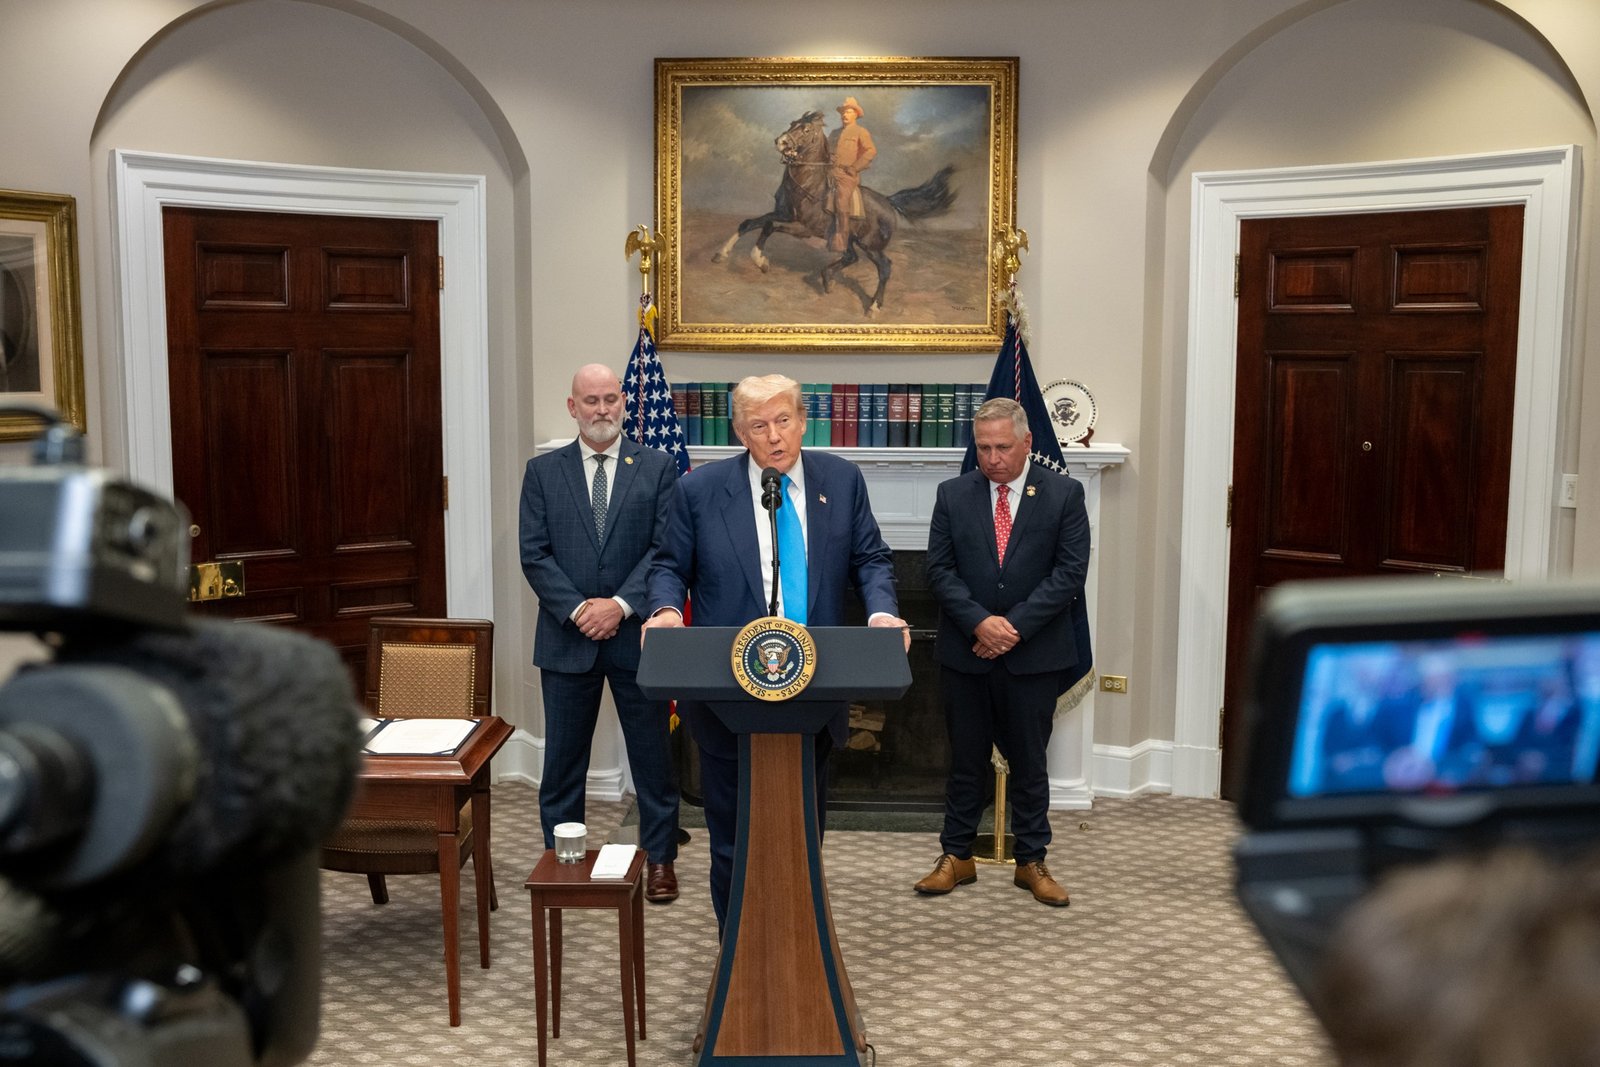
The VA Home Loan Program Reform Act is signed into law, July 30, 2025. (Official White House photo by Joyce N. Boghosian, public domain)
The 2027 COLA has not been announced yet. It will match the Social Security increase for 2027, and the bill to apply it to VA compensation and DIC on December 1, 2026 (H.R. 8552) is pending in Congress. Increases are automatic for current beneficiaries. Over the past decade, the annual COLA has averaged about 3.1 percent.
2026 Monthly Compensation
Veteran alone, no dependents • effective Dec. 1, 2025
| 10% | $180.42 | 60% | $1,435.02 |
| 20% | $356.66 | 70% | $1,808.45 |
| 30% | $552.47 | 80% | $2,102.15 |
| 40% | $795.84 | 90% | $2,362.30 |
| 50% | $1,132.90 | 100% | $3,938.58 |
Rates with a spouse, children, or parents are higher at 30% and up. Full tables: va.gov/disability/compensation-rates.
VA home loans: no down payment for most
VA-backed and VA direct home loans help veterans, service members, and survivors buy, build, improve, or refinance a home. You still need the required credit and income, but terms are often better than a traditional loan: nearly 90 percent of VA-backed loans are made with no down payment, and there is no monthly mortgage insurance. Start by requesting a Certificate of Eligibility (COE).
If you have full entitlement, VA sets no loan limit, as long as you can afford the loan and the appraisal supports the price. VA guarantees up to 25 percent of a loan over $144,000.
The funding fee
Most borrowers pay a one-time VA funding fee, which can be financed. First-time purchase fees are 2.15 percent with less than 5 percent down, 1.5 percent with 5 percent down, and 1.25 percent with 10 percent down; after first use, the fee is 3.3 percent with less than 5 percent down. An interest rate reduction refinance (IRRRL) is 0.5 percent. You do not pay the fee if you receive VA compensation for a service-connected disability, receive DIC as a surviving spouse, or meet certain other conditions. If you are later awarded compensation retroactive to before your closing, you may get a refund.
Behind on payments? New help
The VA Home Loan Program Reform Act (Public Law 119-31), signed July 30, 2025, lets VA pay a loan holder what is needed to avoid foreclosure and sets up a five-year Partial Claim Program for VA loans on primary homes that are in default or at imminent risk of default. If you are struggling, contact VA before you fall further behind.
Your money checklist
- Know your rate (VA.gov): Check your 2026 rate in the full compensation tables.
- Watch the COLA (SSA and H.R. 8552): The 2027 increase follows SSA’s announcement.
- Buying a home? (Certificate of Eligibility): Request your COE before you shop.
- Behind on payments? (Partial Claim Program): Contact VA before you fall further behind.
Sources: VA.gov compensation rates, home loans, funding fee, and entitlement pages; SSA news release, Oct. 24, 2025; Federal Register, Feb. 17, 2026; Congress.gov, H.R. 1815 and H.R. 8552.